VERO BEACH NEW CONSTRUCTION · NOVEMBER 2026
New-Home Buyers Are Getting a 5% Mortgage Rate. Here Is What That Means for New Construction in Vero Beach
Buyers of newly built homes started at an average mortgage rate of 5.01% in the third quarter, more than a full point below resale buyers. In Vero Beach, where builders are heading into their year-end push, the discount is showing up in the payment rather than the price.
Key takeaways
- New-home buyers averaged a 5.01% starting mortgage rate in Q3 2026, versus 6.15% for resale buyers (Realtor.com).
- On 30-year fixed loans the gap was 6.19% versus 6.68%, about $117 a month on a $400,000 home with 10% down.
- Builders discount the rate rather than the price to protect community comparables; 66% used incentives in September (NAHB).
- In Vero Beach, most new construction is on the mainland, and year-end is when builder incentives tend to peak.
The short answer: new construction is cheaper to finance right now
Buyers of newly built homes paid less to borrow than buyers of existing homes in the third quarter of 2026. According to a new Realtor.com report covered by RISMedia on November 17, new-home buyers saw an average starting mortgage rate of 5.01%, compared with 6.15% for existing-home buyers.
On a $400,000 purchase with 10% down, Realtor.com estimates that gap is worth about $258 a month in interest during the first year of ownership. For a Vero Beach buyer weighing a resale home against a builder's spec home at a similar price, that is the difference that should be on the spreadsheet, not the sticker.
Buydown versus a permanently lower rate
Part of that gap is temporary. Many builders fund rate buydowns, in which the builder pays the lender up front so the buyer's rate starts low and steps up over the first year or two. The 5.01% figure is a starting rate, and buyers should treat it as such.
The more durable number is the fixed rate. Realtor.com found that new-home buyers using a 30-year fixed-rate mortgage averaged 6.19%, against 6.68% for existing-home buyers. That half-point spread is worth about $117 a month in interest on the same $400,000 home, and it holds for the life of the loan. Over 360 payments, that is roughly $42,000.
The practical distinction for buyers: a temporary buydown lowers the cost of the first year, while a permanent buydown lowers the cost of every year. When a builder offers incentive dollars, ask what those same dollars would buy if applied permanently to the rate.
Why builders cut the rate instead of the price
Builders sell many homes in the same community over several years. A visible price cut on one home resets the comparable sales for every home that follows it, including homes already under contract that still need to appraise. A rate incentive does not. It changes the buyer's monthly cost while leaving the recorded sale price intact.
Realtor.com senior economist Joel Berner made the same point in the report, noting that the builder's adjustment to affordability "isn't always visible in the listing price." The incentive is widespread: the National Association of Home Builders reported that 66% of builders used sales incentives in September 2026, up from 63% in August.
Timing matters as well. Ali Wolf, chief economist at Zonda and NewHomeSource, expects the incentive trend to continue through year-end as builders work to meet annual sales goals, and described fall and winter as the prime season for new-home shopping. For buyers in Indian River County, December is the month when a builder's quarter and year close at once.
What this looks like in Vero Beach
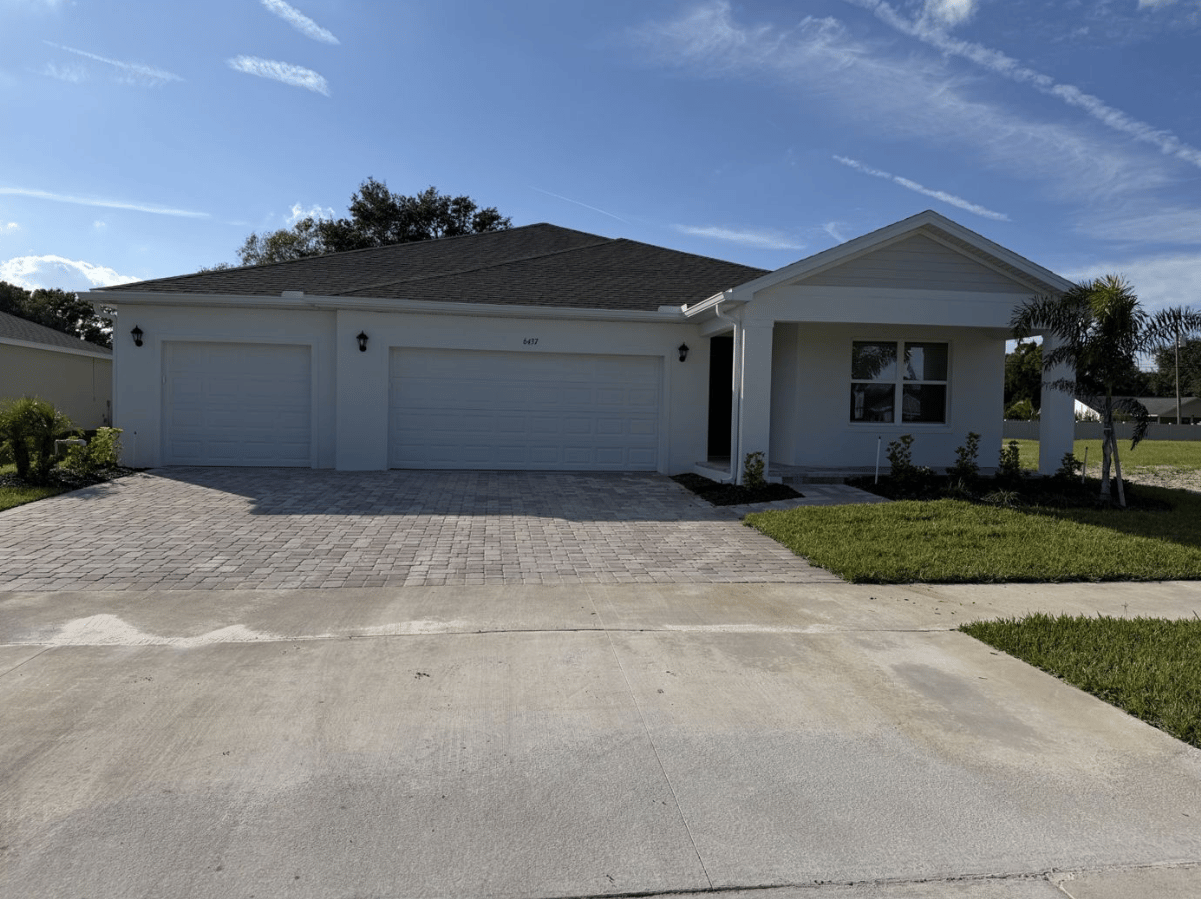
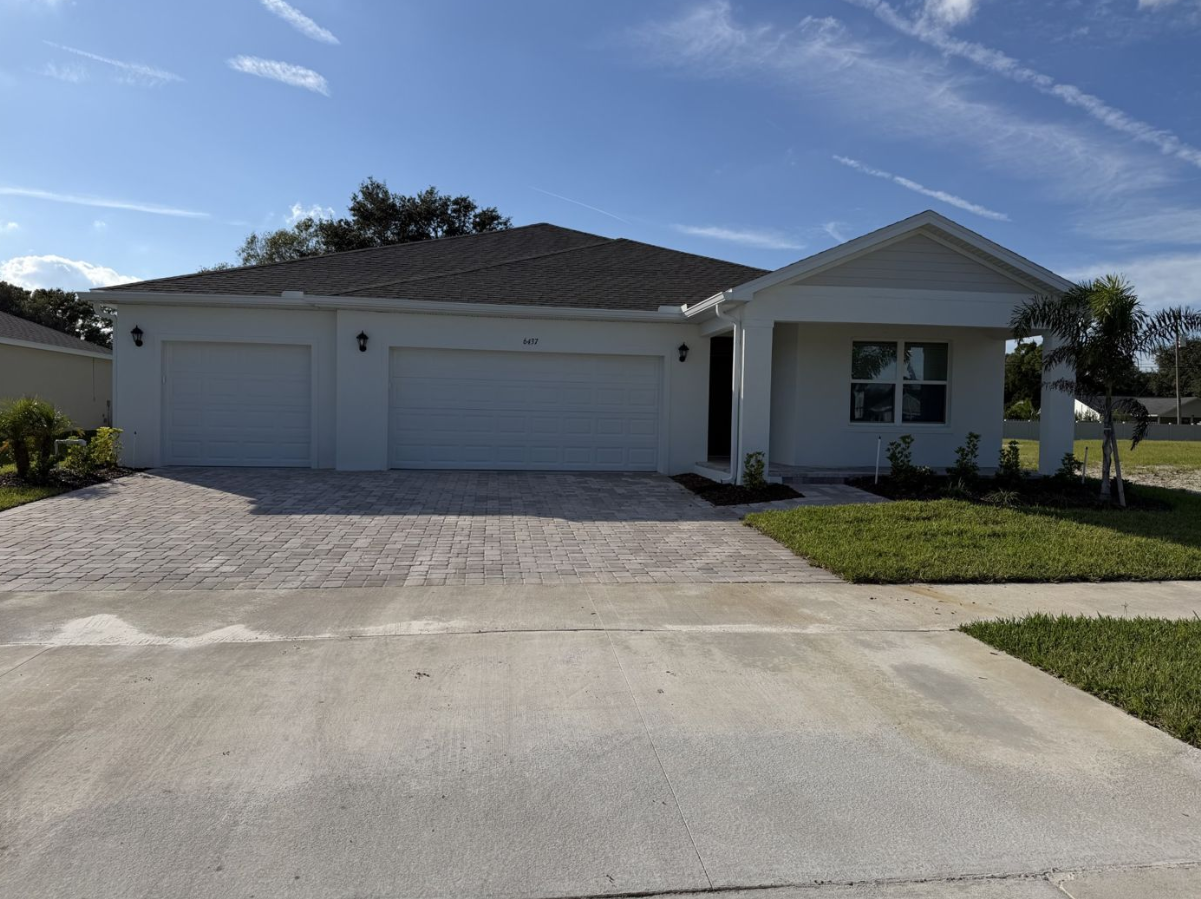
Most new construction in Vero Beach is on the mainland, west of the Indian River Lagoon, where land is available for single-family subdivisions. The product is consistent: single-story concrete block and stucco, three-car garages, paver driveways and covered entries, built to the current Florida Building Code.
That last point has value beyond the mortgage. A new roof, current wind-load construction and, where included, impact-rated openings typically qualify for wind-mitigation credits on a Florida homeowners insurance policy. A new home also arrives without the near-term roof, HVAC and water-heater replacements that a buyer of a 20-year-old resale home should budget for.
The resale side of the comparison is not standing still. Mainland single-family inventory in Vero Beach has tightened in late 2026, which limits a resale buyer's leverage on price. New construction is where the negotiating room currently sits, and it is mostly in financing.
In new construction, the negotiation has moved from the price tag to the payment. Buyers who only compare prices are reading the wrong number.Ben Bryk, Vero Premier Properties
How to evaluate a builder incentive package
Ask for the incentive in dollars. A builder offering a "rate as low as" figure is spending a specific amount with its affiliated lender, and that amount can often be redirected to a permanent buydown, closing costs or a price reduction.
Confirm whether the incentive requires the builder's preferred lender. Most rate incentives do. Get a competing quote anyway so you know what the incentive is actually worth against the open market.
Read the full monthly cost, not only principal and interest. In Florida new-home communities that means HOA dues and, in some subdivisions, a Community Development District assessment that appears on the property tax bill. Two homes with the same price and rate can differ by several hundred dollars a month once those are included.
Know what the rate does after the buydown period. If the payment steps up in year two or three, qualify yourself at the higher payment, not the introductory one.
Bring your own representation to the model home
The on-site sales consultant at a new-home community works for the builder. That is appropriate, and it is also why buyers benefit from their own agent on new construction: someone to compare the incentive against resale alternatives, review the builder contract, and track inspections through construction.
Many builders require that a buyer's agent be registered at the buyer's first visit to the community. If you plan to work with an agent, bring them, or register them, before you walk the model.
Our Financial Concierge Desk coordinates lender comparisons and, for buyers relocating to Florida, the domicile attorneys and CPAs who handle homestead and residency questions. For a new-construction purchase, that comparison work is where the incentive is won or lost.
Frequently asked
Are mortgage rates lower on new construction homes?
Yes, on average. In the third quarter of 2026, buyers of new homes had an average starting mortgage rate of 5.01%, compared with 6.15% for buyers of existing homes, according to Realtor.com. On 30-year fixed loans the gap was smaller but still meaningful: 6.19% for new homes versus 6.68% for existing homes.
How much can a builder rate incentive save me per month?
On a $400,000 home with 10% down, Realtor.com estimates new-home buyers saved about $258 a month in interest in the first year at the average starting rate, and about $117 a month for the full term on a 30-year fixed loan. Your figure depends on the price, down payment, and whether the buydown is temporary or permanent.
What is the difference between a temporary and a permanent rate buydown?
A temporary buydown, such as a 2-1 buydown, lowers the rate for the first one or two years and then steps up to the note rate. A permanent buydown lowers the rate for the life of the loan. Builders often fund either; ask what the same incentive dollars would buy if applied permanently.
Is now a good time to buy a new construction home in Vero Beach?
Late fall and winter is typically strong for new-home buyers because builders are working to meet year-end sales goals, and 66% of builders nationally were using incentives as of September 2026, per NAHB. In Vero Beach, most new construction is on the mainland west of the Indian River Lagoon, where resale inventory has tightened, so builder financing incentives are currently where buyers have the most leverage.
Do I need my own real estate agent to buy a new construction home in Vero Beach?
It is not required, but it is advisable. The builder's on-site sales consultant represents the builder. Your own agent can compare the incentive against resale options, review the builder contract and track construction. Many builders require the buyer's agent to be registered at the first community visit.
Vero Beach luxury homes for sale · Grand Harbor homes for sale · Vero Beach housing market, October 2026: mainland vs. barrier island